The AI power buildout just created the best income opportunity in 25 years
The Incredible Dividend Map…
Where Stocks Yield Up to 48.6% a Year
How 42 essential-service stocks are paying us as much as 48.6% a year for every dollar invested and why the AI electricity supercycle could make the next few
years the best in the map’s 36-year history.
From the Desk of Robert Rapier
Chief Investment Strategist, Utility ForecasterChemical engineer • Energy investing expert • Author of two books • Featured expert on 60 Minutes
Dear Income Seeker,
Quick question.
What’s the highest-yielding stock you’ve ever owned?
Did it pay you 6%? 8%? Maybe even 10% in a very good year?
The stocks on the map I’m about to show you blow those numbers out of the water.
One of them pays us 48.6% a year on what we originally invested.
Another pays 44%. Another 39.5%. Seventeen of them pay us more than 10% a year on our original cost — every year, before the share price moves a penny.
And fifteen of them have now returned to us more than the entire purchase price in cash dividends alone.
These stocks are paying us more than ever before because, for the first time in 20 years, demand for what these companies sell is surging.
AI data centers. Electrification. Industrial reshoring. The CHIPS Act.
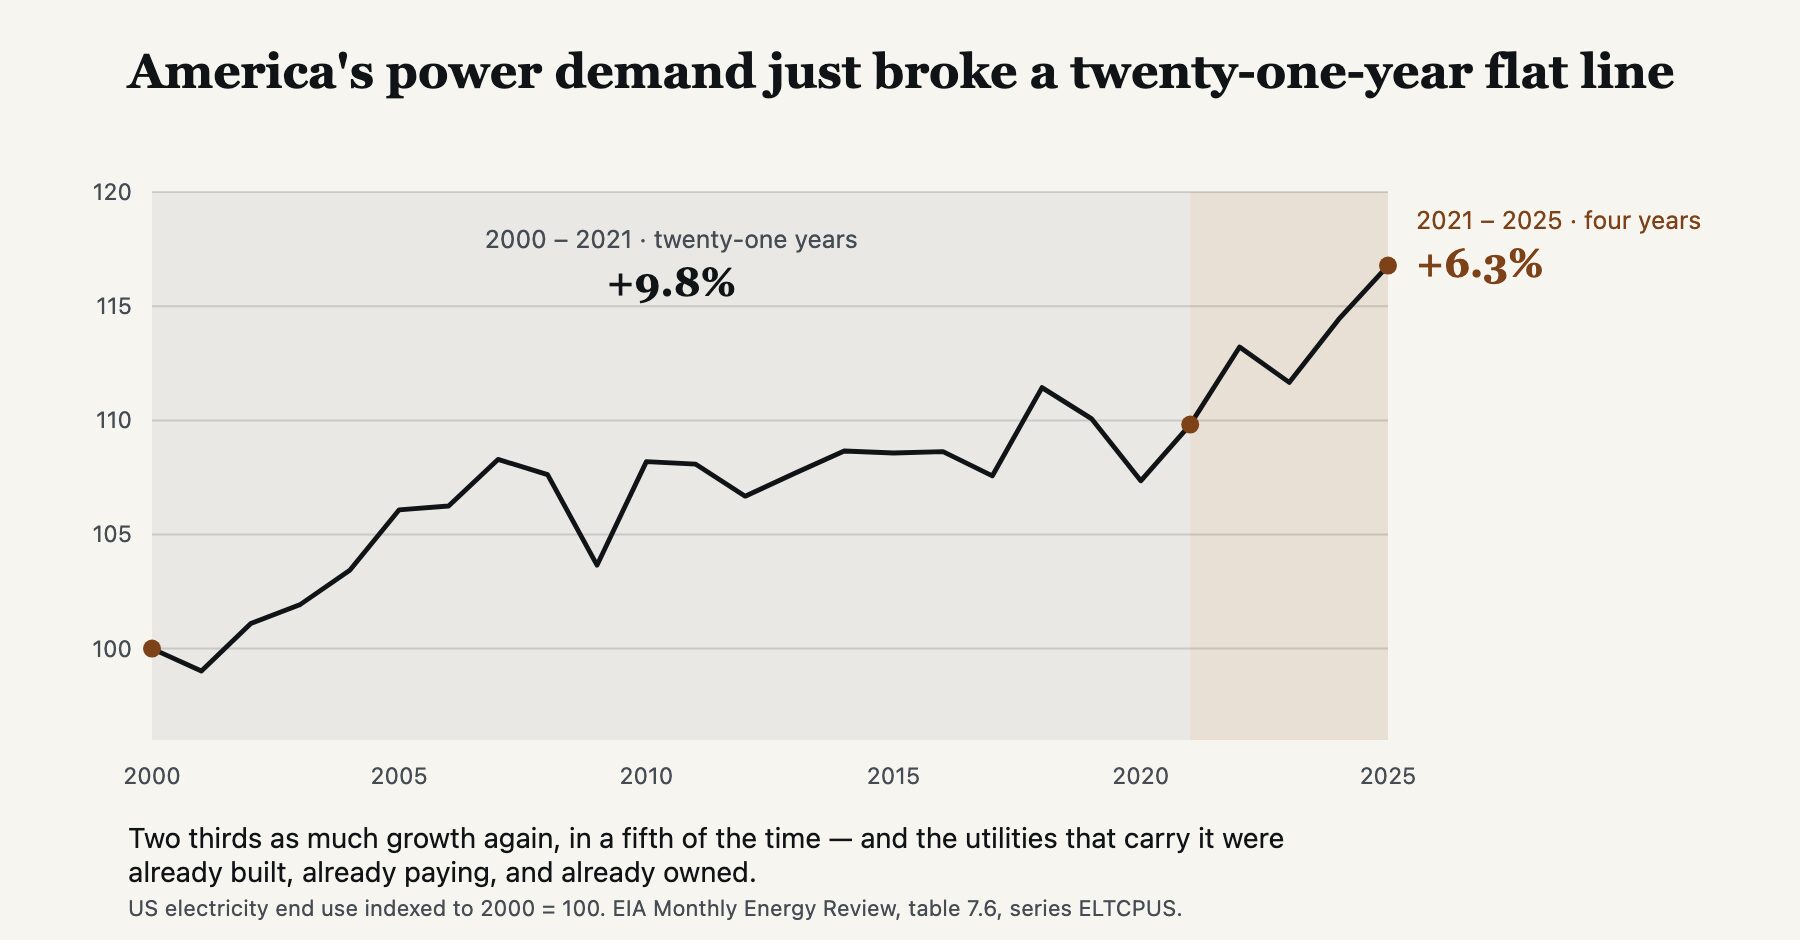
Together, they’ve ignited the strongest period of electricity demand growth since 2000 — according to the U.S. Energy Information Administration.
The companies that own the physical infrastructure this new economy depends on? They were already paying us handsomely. Now their earnings are accelerating — and so are their dividends.
Now is your chance to get in on the ground floor of the next great income opportunity.
What I’m Actually Talking About
Let me put the real numbers in one place, because they sound invented until you see how they
were built.
Across the 42 dividend-paying companies in the portfolio, as of August 20, 2026:
17
Paying over 10% on cost
every year, on their original purchase price, before the share price moves
15
Fully repaid in dividends
have returned more than their entire purchase price in cash alone
48.6%
The highest
a year on cost, on a position held 32 years
9.6%
Typical position
a year compounded — with every closed position and every loss added back in
That last number is the one I would check first if I were you.
Most track records improve when you quietly drop the failures. Ours barely moves. A
figure that survives having the losers added back is a figure that survives being
checked — and you should apply that test to every letter you read, including
this one.
Here is what has changed, and why I am writing to you now.
For the first time in a generation, demand for what these companies sell is growing again.
And it’s happening faster than anyone expected.
For twenty years, American electricity demand was flat. Efficiency gains cancelled out
population growth. These businesses collected their revenue, raised their dividends a little
each year, and generated almost no excitement whatsoever.
That period is over. Data centers, electrification and industrial reshoring have ended it.
These companies were already paying us well through the flat years. What changed is on the
other side of the ledger — and I can show you it in their own quarterly filings, which
I will do on this page.
The AI electricity supercycle just gave these stocks the strongest demand tailwind in
25 years.
These companies were already paying us well. Now their earnings are accelerating — which
means the dividends are about to accelerate too.
Past performance is not a guarantee of future results. All investing involves risk.
Yield-on-cost figures reflect actual portfolio positions measured against their original
purchase prices and depend on how long a position has been held; someone buying today would
start at today’s yield. Counts are measured across the 40 holdings with continuous price
history back to their entry date — two of the 42 do not have it, so 17 and 15 are floors.
Figures as of August 20, 2026.
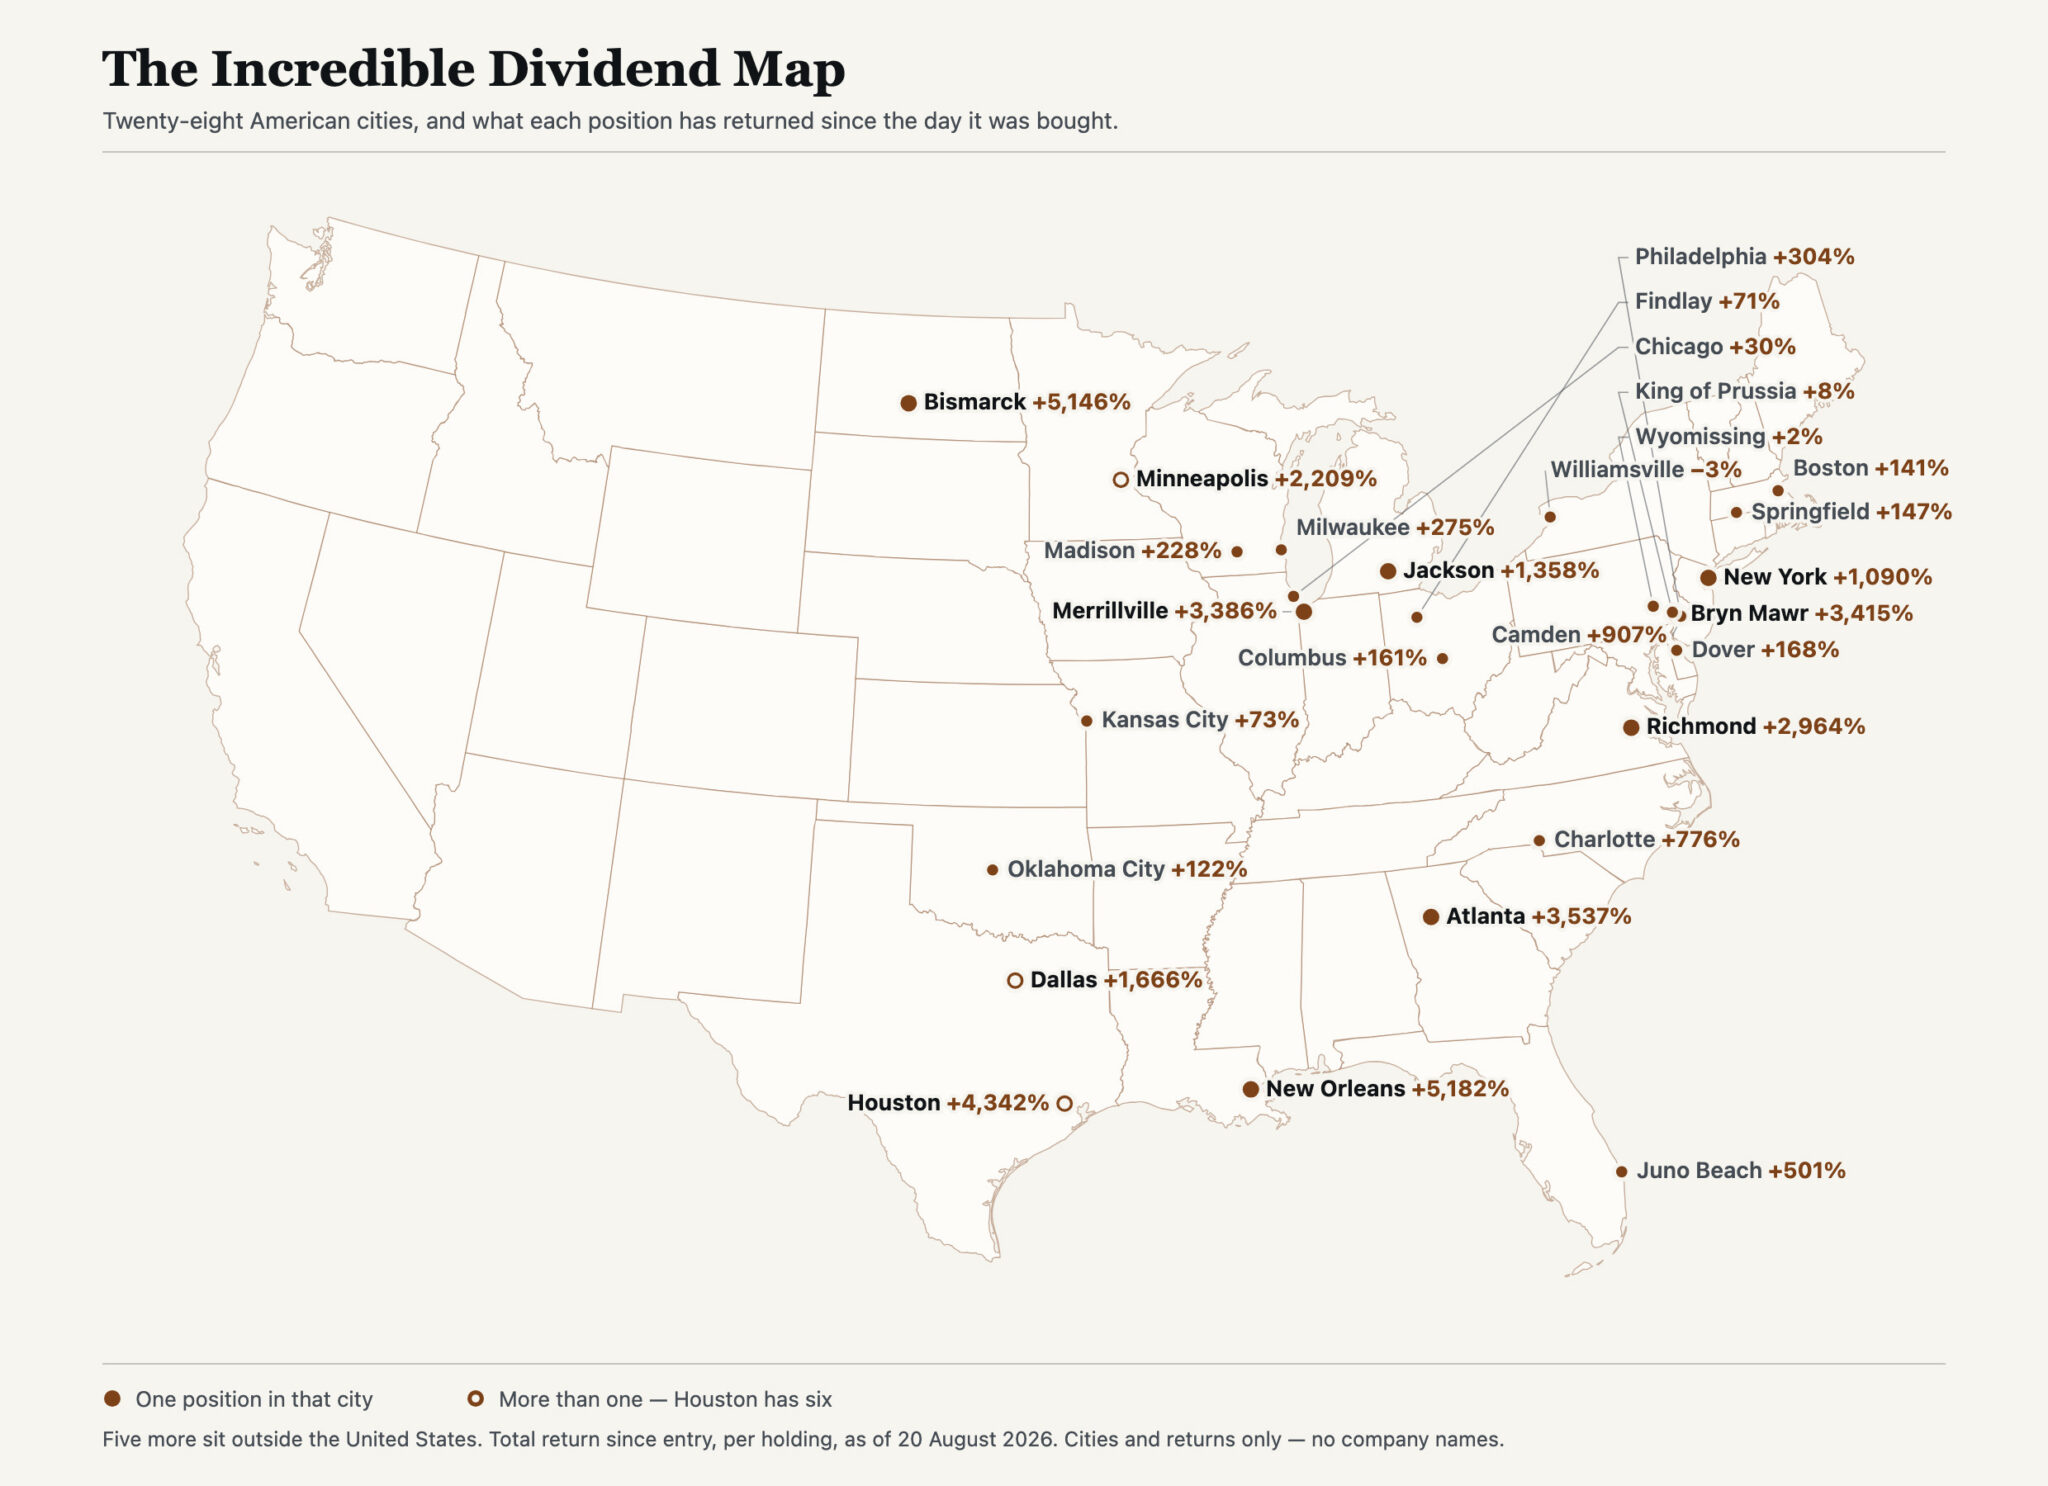
42 Stocks Across 33 Cities
I had the team pin every holding to the city its business actually runs out of. What came back
was a map of America — and it explains the whole strategy better than any chart I could
draw.
Bismarck, N.D.
Up 5,146% · paying 39.5% on cost
A multi-utility bought in September 1990. Electricity, natural gas and construction
materials across the northern plains. Unglamorous in every possible way. Thirty-six years.
New Orleans
Up 5,182% · paying 26.1% on cost
A Gulf South electric utility, bought August 1990. It has been through hurricanes,
bankruptcies elsewhere in its sector, and every kind of regulatory fight.
Outside Philadelphia
Up 3,415% · paying 48.6% on cost
A pure-play water utility, bought August 1994 at $2.86 a share. It has returned more than
six times its purchase price in dividends alone — the position could go to zero and
we would still be up several hundred % on it. Water. Not artificial intelligence, not
biotech. Water.
Houston
Up 4,342% · paying 44% on cost
A fee-based midstream partnership bought in April 2000, at the very top of the last
technology bubble — which is a useful detail, because the businesses everyone was
buying that month are mostly gone.
Richmond, Va.
Up 2,964% · paying 19.7% on cost
Bought April 1989, the oldest position on the map. It happens to sit in the middle of the
largest concentration of data centers on earth, which nobody could have known in 1989.
Atlanta
Up 3,537% · paying 26.7% on cost A Gulf Coast multi-utility, October 1994.
Merrillville, Ind.
Up 3,386% · paying 24.4% on cost Gas and electric across the Midwest, November 1991.
Minneapolis
Up 2,209% · paying 12.7% on cost An upper-midwest electric utility, March 1990.
New York City
Up 1,090% · paying 13.9% on cost A telecom leader, November 1991.
Dallas
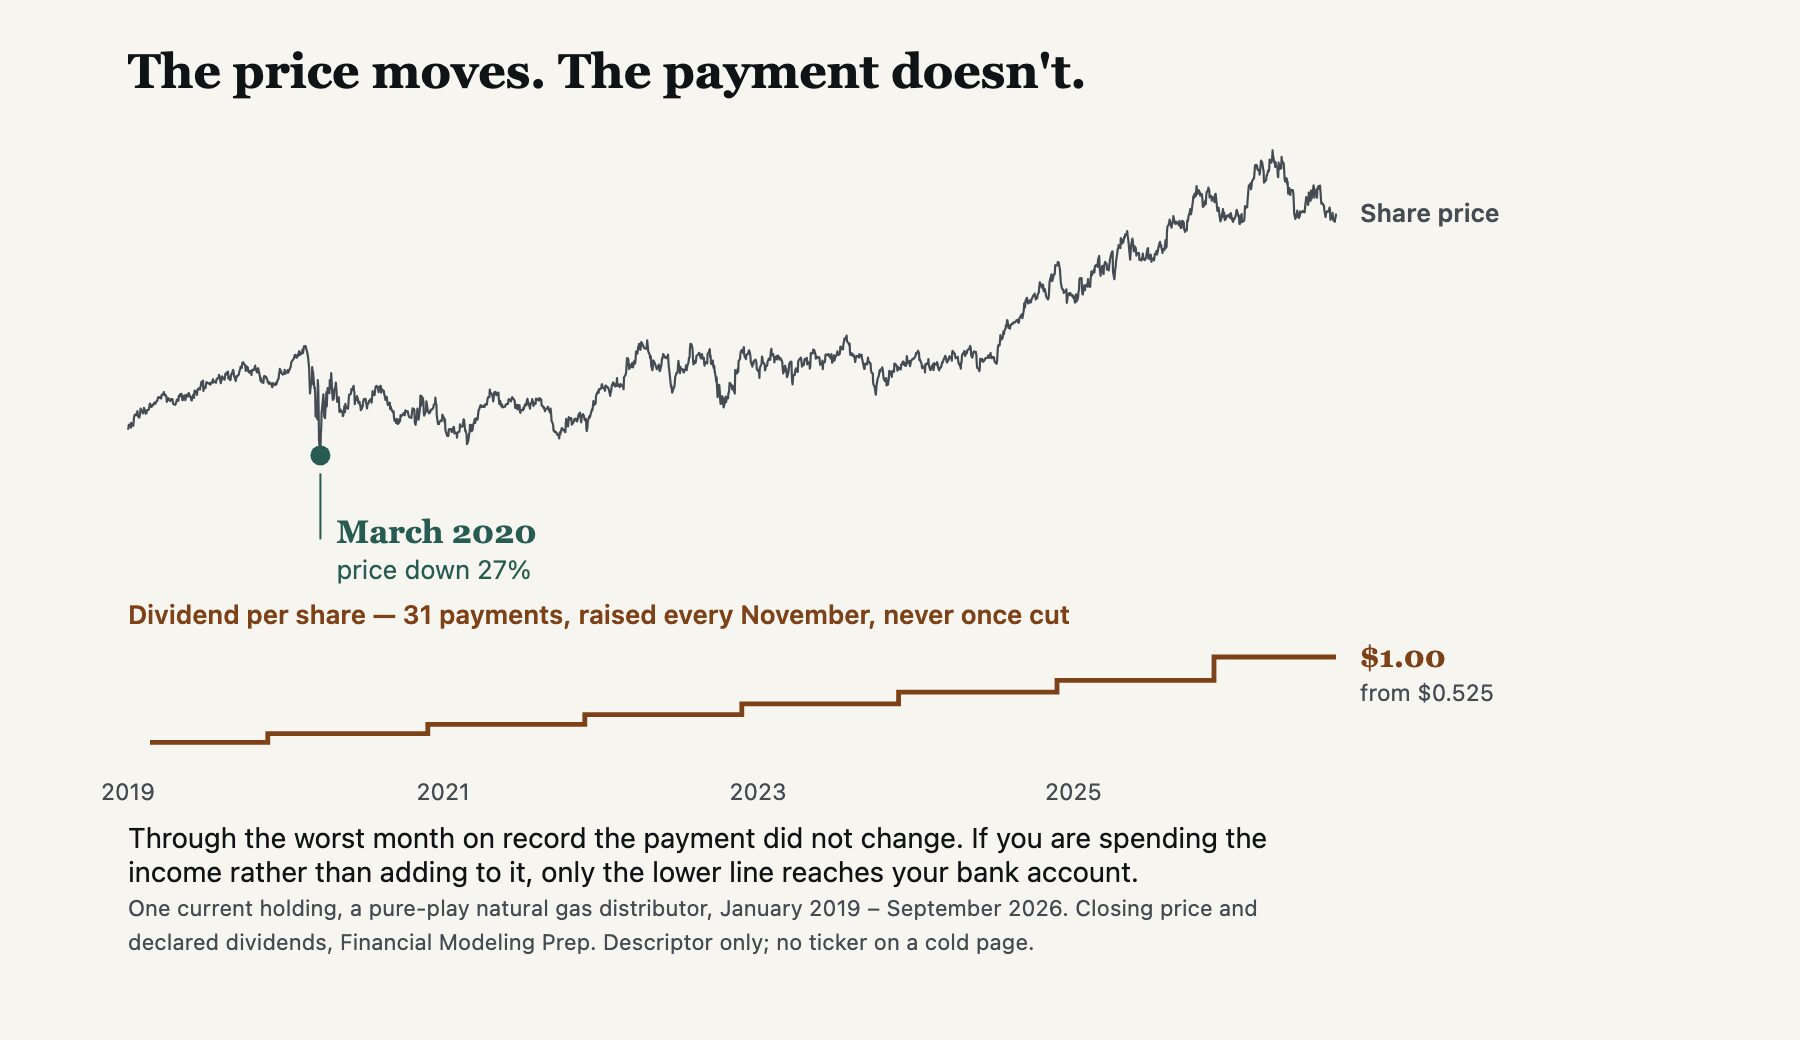
Up 1,666% · paying 16.8% on cost A pure-play natural gas distributor, June 2002.
And there are more — in Wisconsin, Ohio, Oklahoma, Michigan, New Jersey, Massachusetts,
Kansas City, Columbus, Charlotte, Camden. A few outside the United States: Calgary, Toronto,
London.
Thirty-three cities in all.
Some of these firms are massive. Others you have never heard of.
But every number on that map was produced the same way. We bought the company once. The price
we paid never changed again. And the company kept raising what it pays us.
That is the whole engine, and it has a name.
Returns are since our original purchase date and include dividends. Holding periods range from
24 to 37 years — these are multi-decade results, not annual ones. Figures as of August
20, 2026. Company names and tickers are reserved for members.
How Yield on Cost Actually Works
Let me explain yield on cost properly, because once you see it you cannot unsee it —
and practically every income letter you have ever read has skipped it.
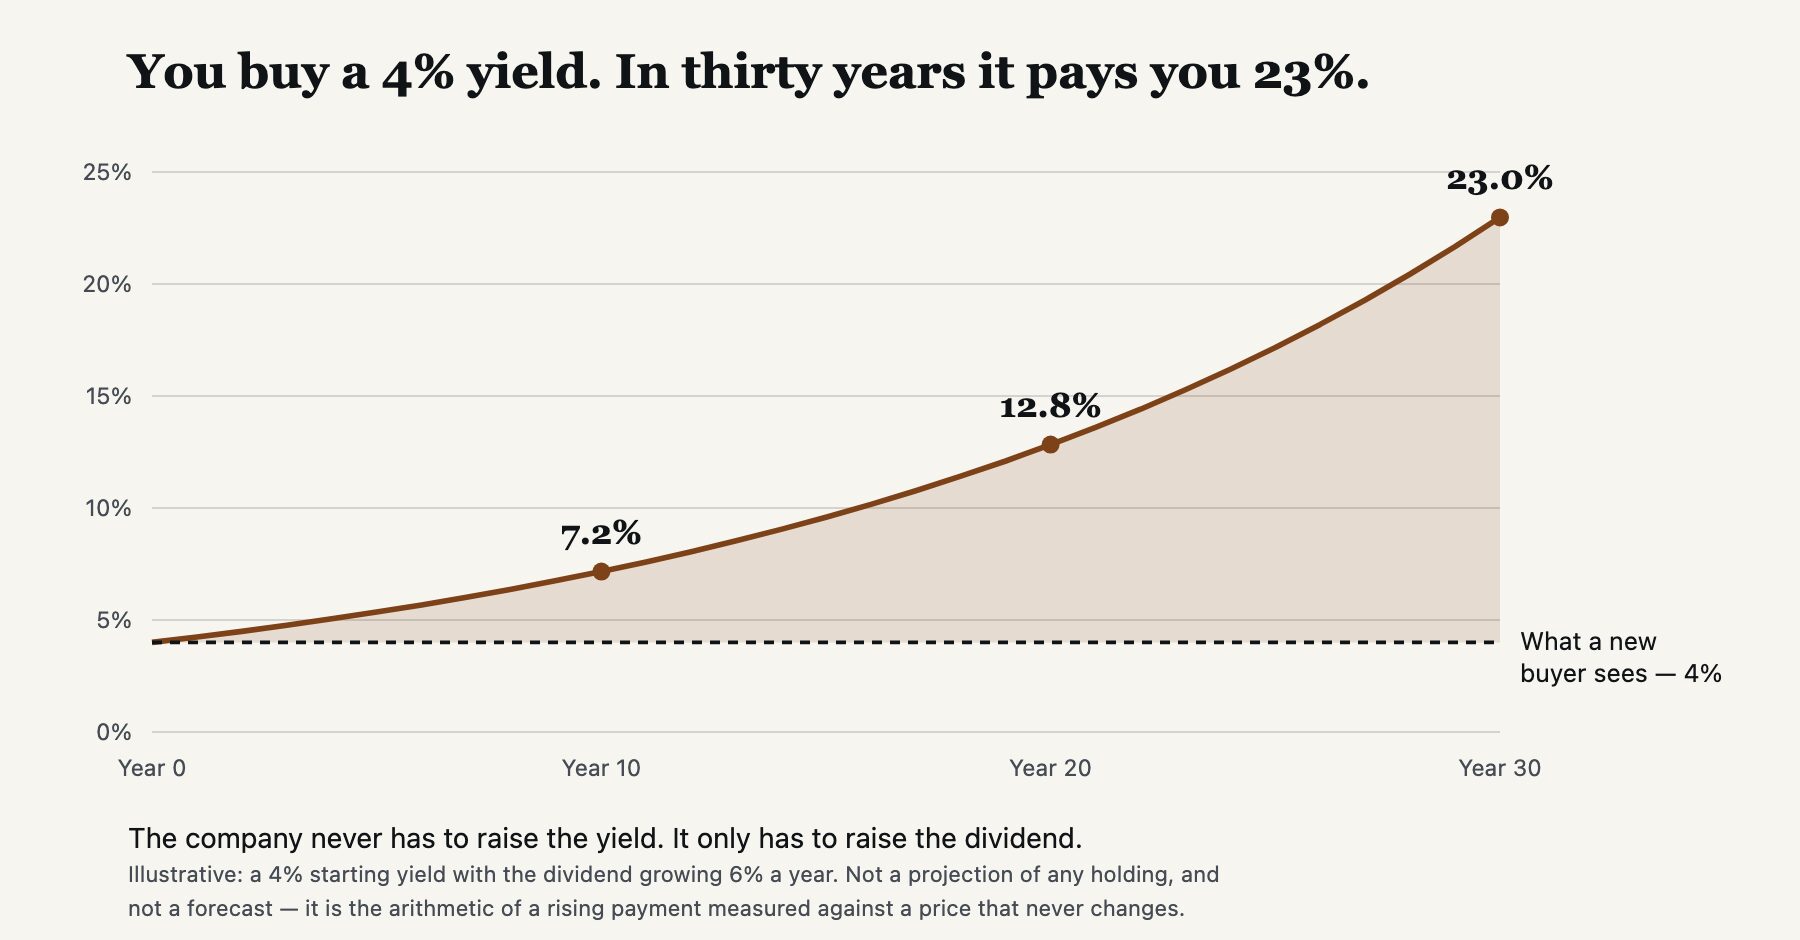
Say you buy a stock today at $100 that pays $4 a year. A 4% yield. Respectable, not thrilling.
Now the company raises its dividend 6% a year — ordinary for the businesses I follow.
After 10 years
7.2%
Your $4 has become $7.16 — on your original $100
After 20 years
12.8%
$12.83 a year
After 30 years
23%
$22.97 a year, on money committed three decades earlier
Notice what is not in that calculation: the share price. It could have tripled, or gone
sideways, and none of these numbers change. Your yield on cost is fixed by two things
only — what you paid, and what the dividend has done since.
The stock’s current yield may still show 4%, because the price rose alongside the
dividend. A new buyer gets 4%. You get 23%. You are looking at the same ticker and receiving
completely different things, and the only variable is when you started.
Now raise the growth rate. Many of the companies on this map have compounded their dividends
faster than 6% for decades. At 7–8%, thirty years produces a yield on cost above 30%.
Push it to a company bought at $2.86 in 1994, and you arrive at 48.6%.
Here is a subscriber describing the same mechanic in his own words:
I bought 9,000 shares [of a midstream holding] at an average cost of $11.80. After deducting
the dividends [as return of capital], I have a new cost of $9.00 a share with a $2.75
dividend — or 30.55% on invested capital. Can’t beat that with a stick!
Joe Lindell · subscriber survey, 2021
That curve assumes the dividend grows 6% a year. Hold that number. Later in this letter I am
going to show you why the companies on this map are about to grow their dividends faster than
they have in twenty years — and when the growth rate rises, this curve does not simply
shift upward. It steepens. A new investor today does not need thirty years to reach a
double-digit yield on cost.
That is what this particular moment is actually offering. Not a stock that doubles.
A compounding curve that got steeper.
The Raise Season Nobody Watches
The yield-on-cost math I just walked you through only works if the dividend actually grows.
So let me show you the calendar.
Eight of the companies on this map raise their dividend in the autumn —
between September and the end of December, most of them in November, most of them within days
of the same date every year.
Five of them have not missed once since 2019.
Month
Company
Record since 2019
October
An Oklahoma electric utility
7 of 7
November
The largest transmission network in the United States
7 of 7
November
A pure-play gas distributor in Dallas
7 of 7
November
A Gulf South utility in New Orleans
7 of 7
November
A central-plains utility in Kansas City
7 of 7
Seven raises in seven years, each of them, no exceptions.
Already on the record
A midstream partnership in Findlay, Ohio has told its investors what to expect: distribution
increases of 12.5% this year and 12.5% again next year.
A 12.5% raise does not lift your yield for a quarter. It lifts it permanently, on the price you
originally paid, and then the next raise builds on top of it.
That is the engine. It is not a forecast. It is a calendar, and you can look it
up.
Dividend-increase records compiled from each company’s payment history since 2019, as of
August 31, 2026. Distribution guidance is management’s own. Past performance is not a
guarantee of future results and no dividend is guaranteed.
Why These Companies Can Pay What They Pay
Now the three characteristics.
They sell something people cannot go without
Power, water, natural gas, connectivity, and the pipelines underneath all of it. Demand
does not vanish in a recession. Nobody cancels electricity.
Most face little or no competition
There is one set of wires to your house. There is one water main. Building a second is
not merely expensive; it is usually illegal.
They earn a return on what they invest
Many operate under an arrangement in place since an 1865 Supreme Court decision. In
exchange for accepting public oversight and an obligation to serve everyone in their
territory, they are granted the opportunity to earn a fair return on the capital they
put in the ground.
Sit with that third one, because it is the engine of everything on this page.
So when demand rises and they are required to build — new transmission, new generation,
new pipe — that construction does not merely cost them money. It becomes the
basis on which they are permitted to earn. Earnings rise. And the dividends funded by those
earnings rise with them.
More demand → more investment → higher earnings → bigger dividends.
For two decades there was very little new demand to serve, so this engine idled. Our dividends
grew anyway, modestly and reliably, which is how a $2.86 water utility becomes a 48.6% yield
on cost.
That engine sat idle for twenty years. It is not idle now — and what
changed is worth showing you in detail.
All 42 companies, all 33 cities, and what each one pays on the money originally invested.
The Biggest Electricity Demand Surge Since WWII — And Why It Changes Everything
You have heard about the AI boom. Everyone has.
Every AI query travels to a data center: a warehouse-sized building filled with specialised
processors that draw an extraordinary amount of electricity. There are now roughly
a billion people using a single AI service every week, and that is one
service among many.
Here is what that has done to the numbers:
4.4% → as much as 15.3%
Data centers used 4.4% of America’s electricity in 2023. The Department of
Energy’s own national laboratory now projects 9.5% to 15.3% by 2030 — a
doubling to a tripling of an already-enormous load, inside seven years.
2,300 gigawatts stuck in line
That is the national interconnection queue — power projects that are financed,
approved, and waiting on a grid with no room for them. For scale, the entire United
States runs on roughly 1,200 gigawatts of capacity today.
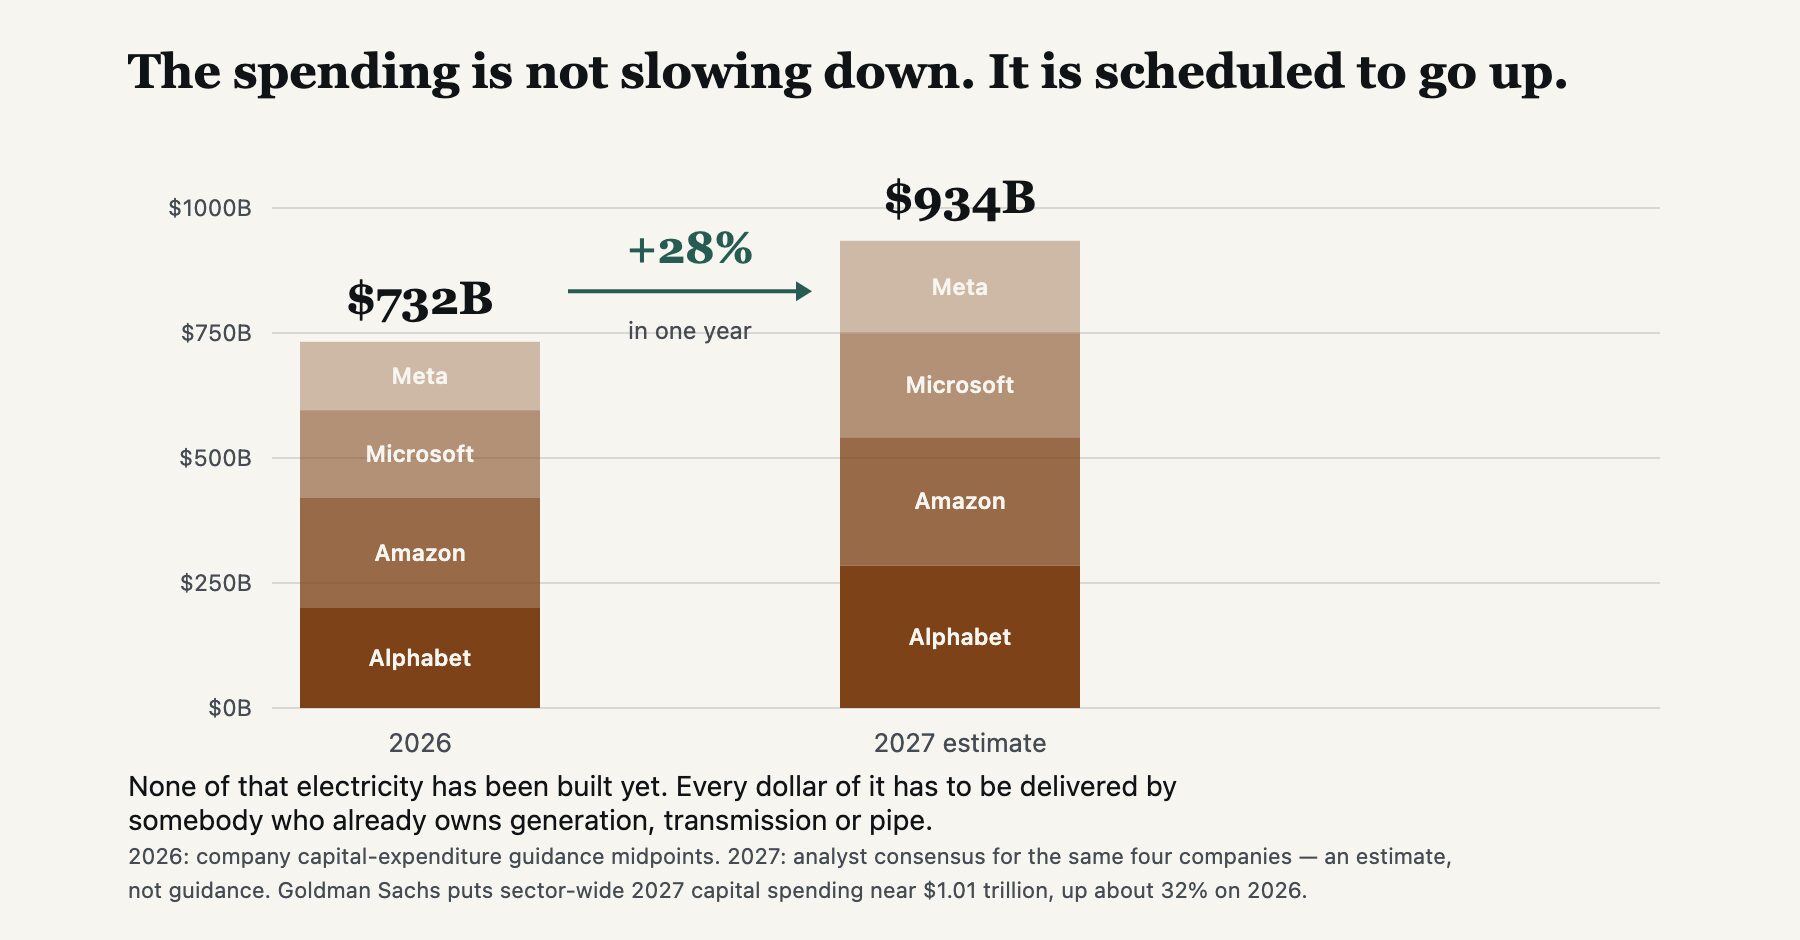
$195–205 billion, and its first negative free cash flow
Alphabet raised its 2026 capital budget to $195–205 billion, told investors 2027
would climb further still, and posted the first negative free cash flow in the
company’s history to pay for it.
$220 billion — and still not enough
Amazon lifted its own to roughly $220 billion. Its chief executive said that even at
that number, “we will still not have enough capacity to meet all the demand we
have in 2026.”
Read those last two again. Two of the most profitable enterprises ever built are spending more
than their operations generate, and telling shareholders it still is not enough.
And it is not close to finished. Those four companies are on track to spend roughly
$934 billion next year — another 28% on top of a number that already
has no precedent. Goldman Sachs puts the whole sector past a trillion dollars in
2027.
This is the largest capital buildout in human history, and it is still accelerating.
And none of that money produces a single thing until somebody delivers the power.
Not a chip. Not a model. Not a query. Electricity has to arrive first, at a scale and
reliability that did not previously need to exist.
This is not a growth story. This is a fundamental rewrite of how America generates and
consumes electricity.
The last time American electricity demand did anything like this was the Second World War.
Demand rose 60% between 1939 and 1944, while the country turned itself into
the arsenal of democracy. The energy consultancy Wood Mackenzie has drawn exactly that
comparison about what is happening now.
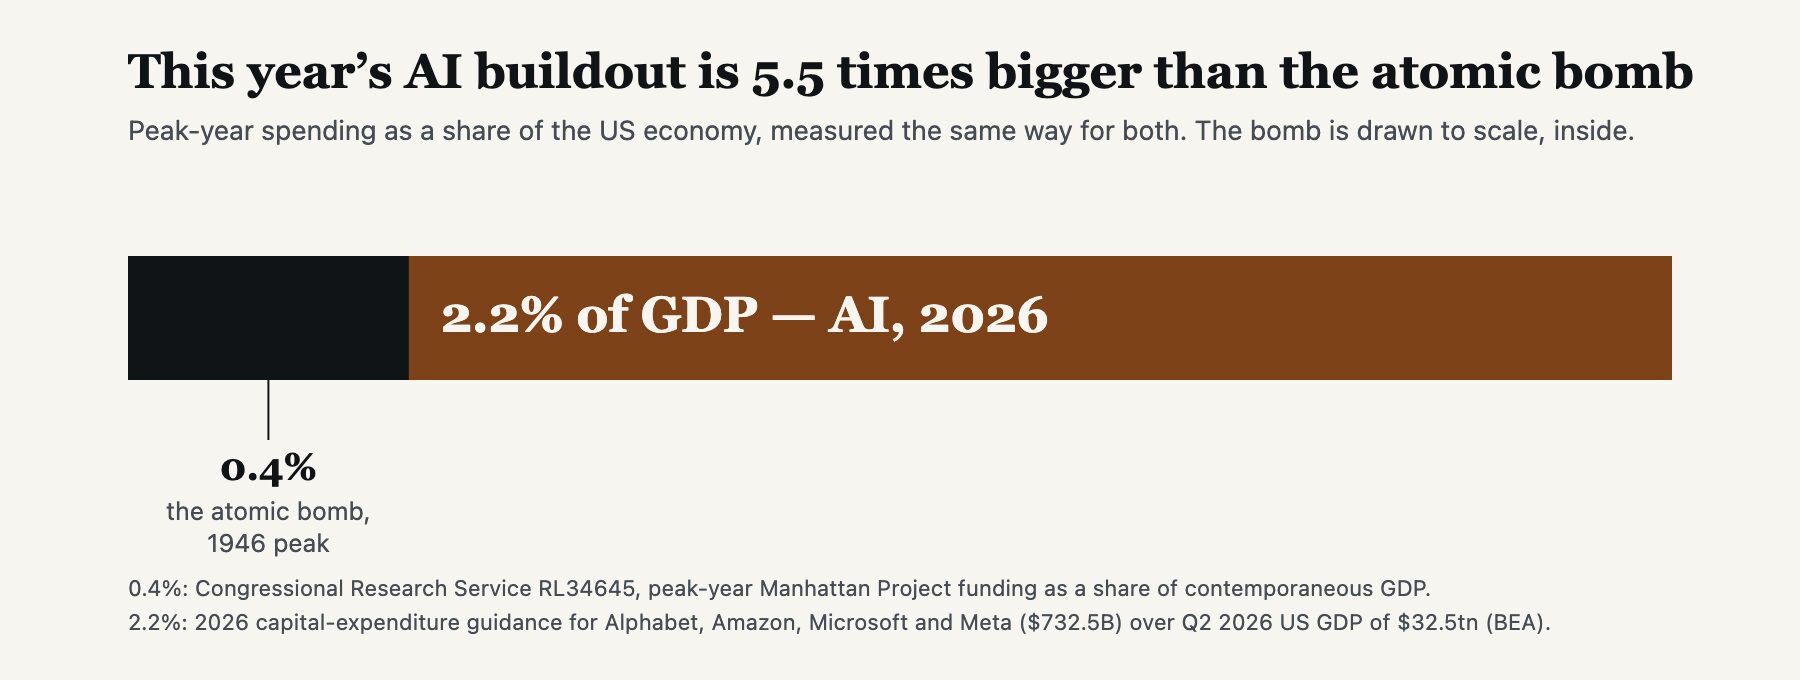
That is how the demand compares. The check being written compares to the bomb.
At its 1946 peak, the Manhattan Project consumed 0.4% of U.S. GDP. Four
American technology companies have guided to about $730 billion this year —
2.2%. Not the war. The bomb.
We are in the middle of a wartime-scale power buildout — and almost nobody outside the
energy industry has connected it to their income portfolio yet.
Go back to the map for a moment. Every one of those companies owns a piece of what this money
has to be spent on — the generation, the wires, the pipe, the water. They are not
competing for the AI prize. They are the ones being paid to make it possible,
by customers who have already committed the budget and cannot walk away from it.
One of them has been paying us 48.6% a year on what we originally invested
since 1994 — through the flat decades, before any of this. Now the biggest capital
program in history is arriving on top of it.
The Waiting List to Bring Power Online Has Never Been Longer
There is a name for what is holding all of this back, and it is not chips and it is not money.
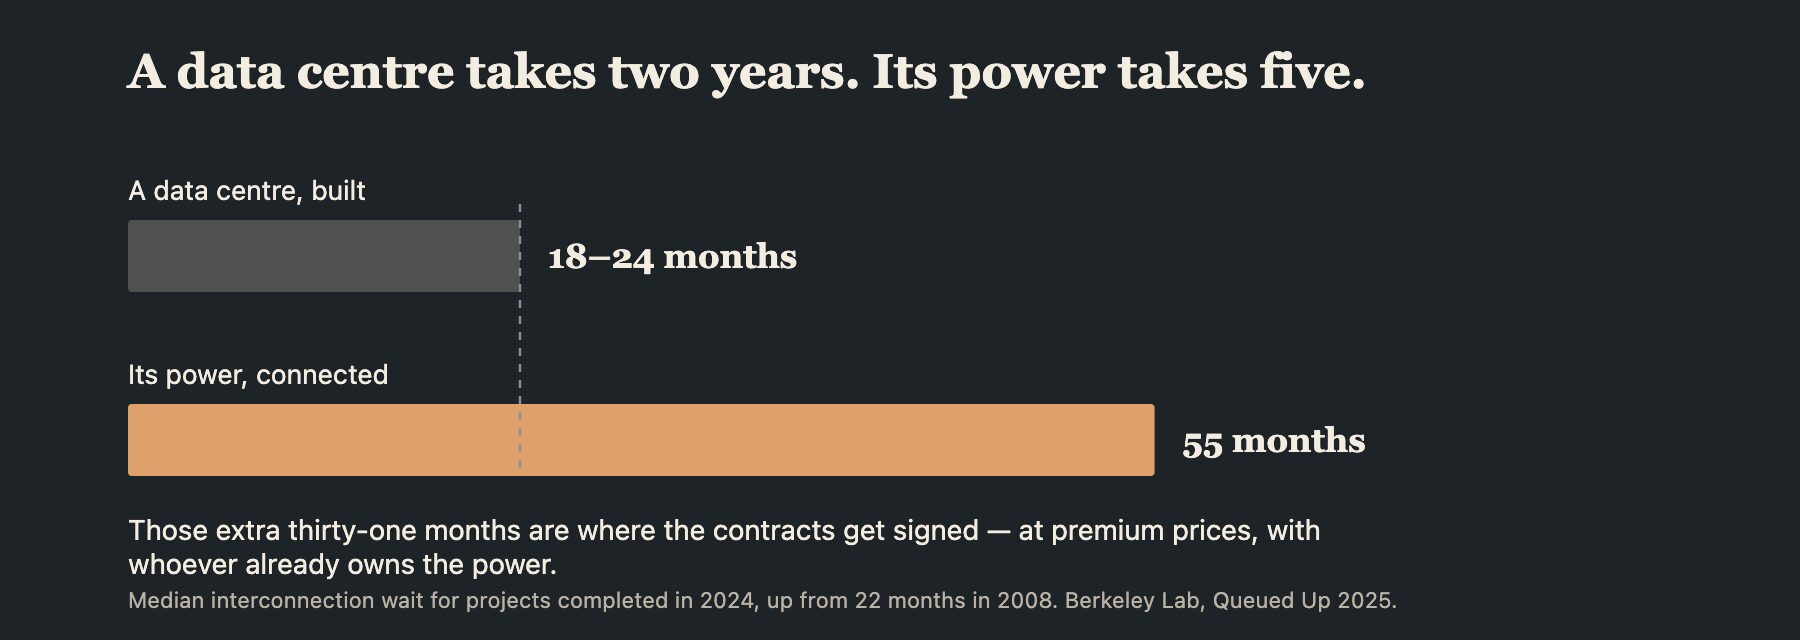
The industry calls it the interconnection queue: the waiting list to plug a new power project
into the grid.
More than four and a half years to connect power that has already been built, financed and
approved, to a grid designed for a country whose electricity demand was not growing.
Do the math and you find the entire investment thesis of this letter sitting in the gap.
The companies building these facilities cannot wait. So they have stopped waiting. They are
going directly to the businesses that already own the generation, the
transmission and the pipelines — and signing twenty- and twenty-five-year contracts at
premium prices to lock the supply up before somebody else does.
Some of those businesses are on this map. We have owned several of them since before the first
commercial web browser existed.
You can watch this happening in the capacity market — where large buyers pay, years
ahead, for a guarantee that power will be there. In America’s largest power market,
capacity prices rose 833% in a single year.
Then they hit the administrative ceiling. And they have now cleared
at that ceiling three auctions in a row.
The market is no longer telling us what power is worth. It is telling us that the cap is the
only thing holding the number down.
You Don’t Have to Guess Which AI Company Wins
You do not have to take my word for what happens when an unglamorous power company gets
discovered.
It has already happened three times in two years, and each time the pattern was identical: a
business Wall Street had priced as a slow-growing utility got repriced as critical AI
infrastructure — because that is what it turned out to be.
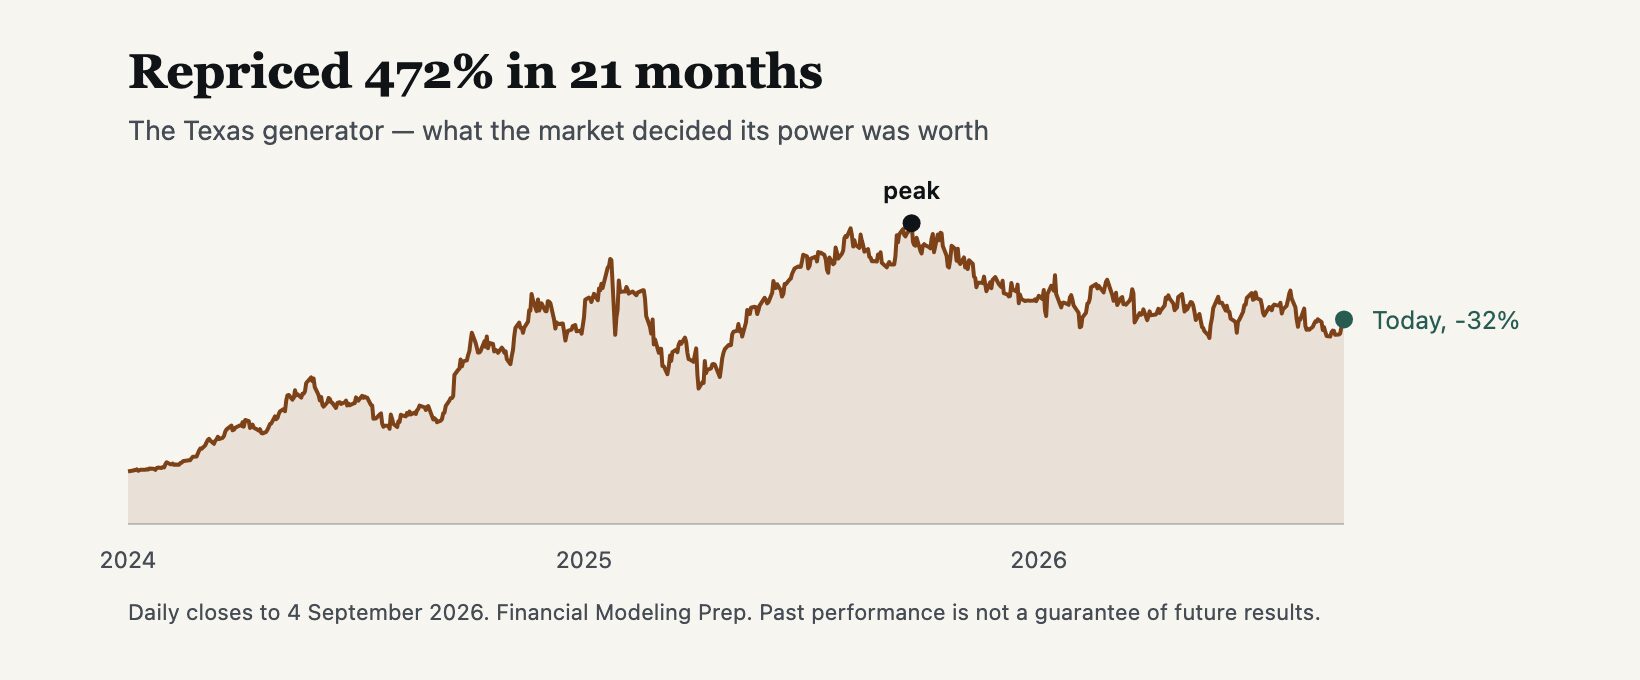
The Texas generator
A company that owned natural gas, coal and nuclear plants across Texas. Nobody wanted them.
Old assets, in a deregulated market, in a state whose grid had recently failed in a way that
made national news. Then data centers started buying Texas power in volume, and the market
realised those plants were the only thing standing between an AI campus and a dark building.
The stock rose 472% in twenty-one months.
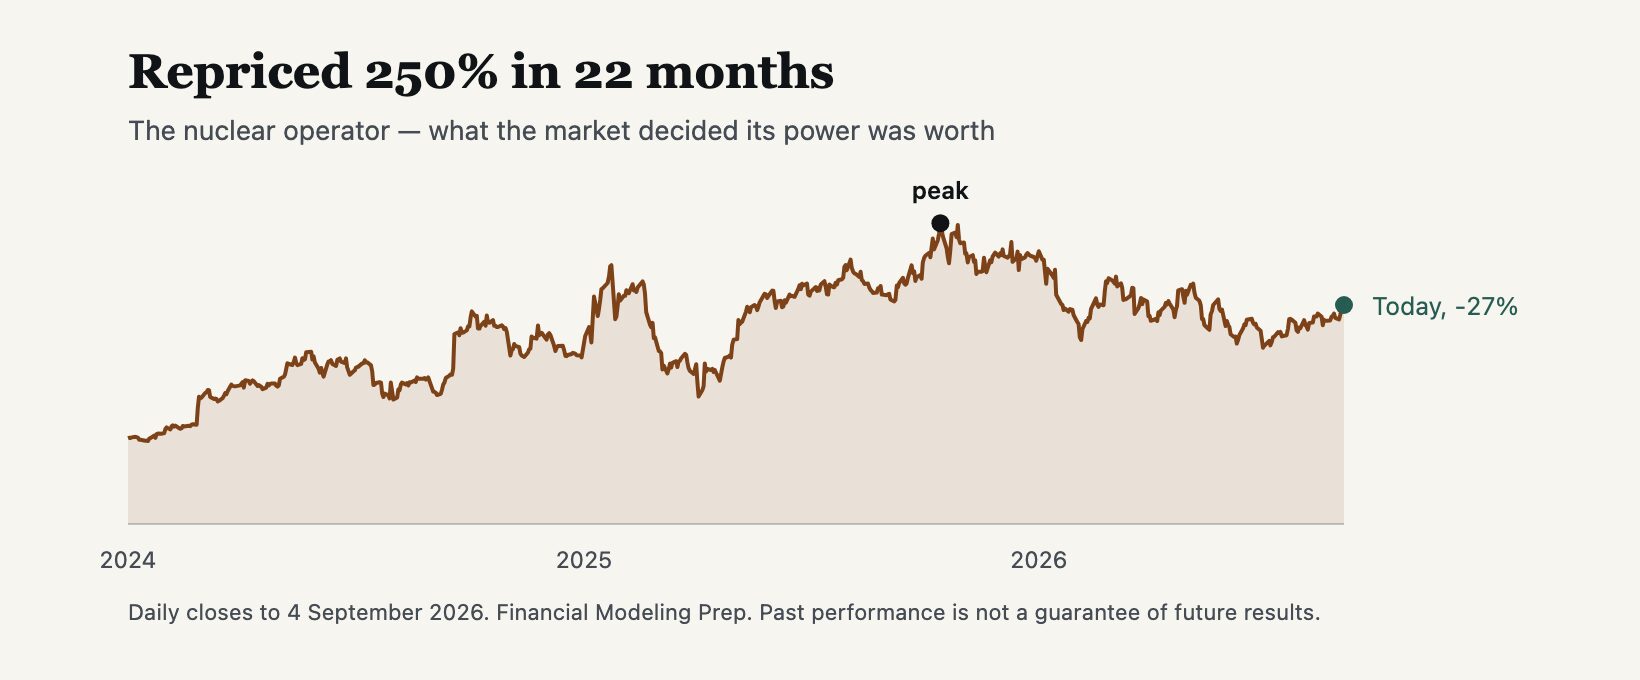
The nuclear operator
It runs the largest fleet of nuclear reactors in the United States — the same reactors
that were being shut down as uneconomic a few years earlier. Then a technology company signed
a twenty-year agreement to restart a shuttered plant and take all of its output. Roughly
250% in twenty-two months.
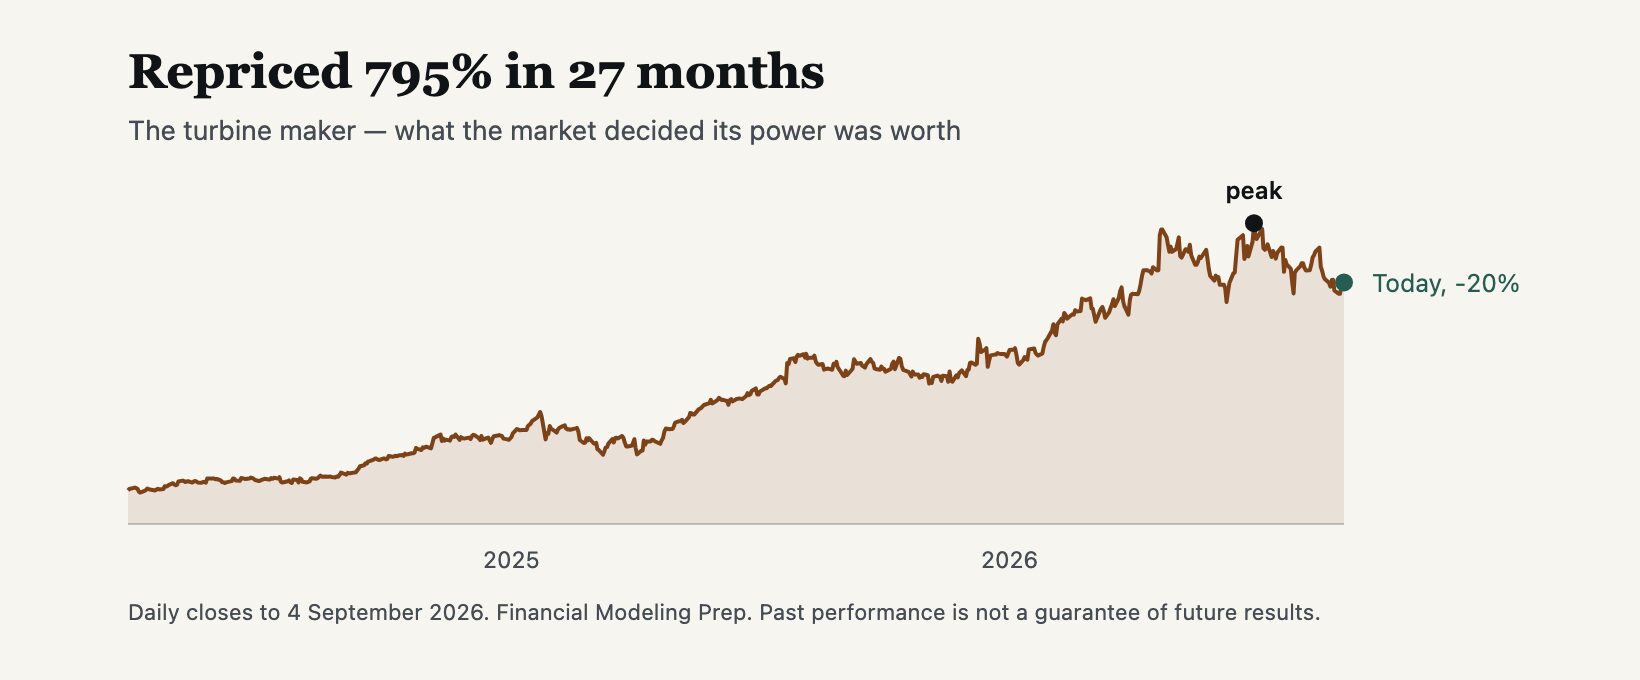
The turbine maker
It builds the gas turbines and grid equipment that power infrastructure is made of. When the
hyperscalers began ordering at unprecedented rates, its order book went vertical — it is
now effectively sold out of turbines for years. 795% in twenty-seven months.
Daily closing prices from the first trading day of January 2024 (or first day of trading) to
4 September 2026. Peak-to-date declines measured from each company’s own closing high.
Past performance is not a guarantee of future results.
Now here is the part a promotion usually leaves out, and I am including it because leaving it
out is how readers get hurt.
Every one of the three is now well below its own peak — by 32%, 27% and 20%.
That is what a fast repricing looks like from the inside. Money rushes in, the multiple runs
well ahead of the business, and then the stock gives a chunk of it back — and the people
who bought at the top spend two years getting even.
Which is exactly why I am not asking you to buy that kind of stock.
The companies on this map are not momentum trades that happen to sit in front of the AI story.
They are income compounders that sit in front of it. We have owned most of them for years or
decades. They pay us whether or not Wall Street is paying attention this quarter, and they
paid us handsomely through twenty years when it definitively was not.
If the market reprices them, wonderful. We just don’t need it to. That
is the whole difference between what I do and what you have been reading about all year.
All 42 dividend payers, every buy-under price, and the full raise calendar.
My name is Robert Rapier, and I am not a Wall Street analyst.
I am a chemical engineer.
I caught the investing bug in high school, in the late 1980s. I credit my algebra teacher, who
spent a lesson showing the class how compounding worked. I was fifteen, from a family with no
money, and I walked out of that classroom understanding that I would be wealthy eventually.
All it would take was time, patience, and not doing anything stupid.
That is still, essentially, my entire investment philosophy.
Then I spent more than three decades inside the energy business before I ever began writing about it.
I ran an engineering team for ConocoPhillips in Scotland, working on North Sea oil and gas
projects. I was a butanol engineer for Celanese in Germany, where I designed a unit that cut
production costs by $5 million a year. I spent two years as an efficiency expert at a Texas
petrochemical plant, where the changes I implemented saved $9 million a year. I have been an
engineering director for an environmental technology company in the Netherlands. I hold
five patents.
Three international postings. Refining, gas production, gas-to-liquids, ethanol, butanol,
petrochemicals.
That background is why this map works.
I know what a pipeline actually does. I know why a gas turbine fails, and what it costs to fix.
I know what it takes to bring a new megawatt online, because I have stood on the site while it
was being built, in a hard hat, in the weather.
When I read a utility’s annual report, I am not reading accounting. I am seeing the
physical plant behind the numbers — and I can usually tell you which of those numbers is
going to move next.
I have written about energy publicly since 2005 — in the Wall Street Journal, the
Washington Post, the Christian Science Monitor and The Economist, and as a senior contributor
at Forbes. I have written two books on energy. I have appeared on 60 Minutes and the History
Channel.
Two Calls, Eight Years Apart
In my first month running this publication, in July 2018, the safest-looking income in the
market was a class of pipeline partnerships. They were toll collectors. Oil could rise or fall
and they still got paid for moving it. Everybody knew this.
Here is what I wrote instead:
Utility Forecaster
Issue of 27 July 2018 · Robert Rapier
Conventional wisdom held that since these partnerships function as toll
collectors… they were more insulated from the price swings that can impact
oil producers.
This is true, but during a long downturn in oil and gas prices, contracts expire and
[they] had to renew agreements under less favorable terms. Many… found themselves
doing what was once unthinkable — they had to cut distributions.
I was not reading the story. I was reading the contracts. That is what an engineer does, and it
is the only real advantage I have ever had.
I told subscribers to hold what they already owned and to add nothing new until the uncertainty
settled. I named the specific risk: that these partnerships would be folded into ordinary
corporations, and that unitholders would get a tax bill they had not asked for.
Fourteen months later, four of the partnerships in our portfolios had been bought out
and eliminated. Three of them folded into a parent or acquiring corporation —
exactly the mechanism I had named. The fourth was taken out for cash.
I did not write a word about being right. I am telling you now only because you have no other
way to judge whether my caution is worth anything to you.
Then, in January of 2026…
I wrote something similar about artificial intelligence. I will give it
to you exactly as it ran, because I want you to be able to hold me to it.
“For most of the past year, investors chased artificial intelligence as if it were a
self-contained trade. Capital flooded into software platforms, hyperscalers, and semiconductor
designers, all on the assumption that AI growth was frictionless and unlimited. It
isn’t.”
“Models don’t train themselves in the cloud. They run on electrons, steel,
land, cooling systems, pipelines, and transmission lines. And those inputs are not infinitely
scalable.”
“That is why the next leg of the AI trade will not be found in technology companies. It
will be found in real assets — utilities, midstream partnerships, select REITs, and
defensive income stocks that own the infrastructure everything else depends on.”
And this, which is the whole argument in one sentence: “For nearly 20 years, U.S.
electricity demand was effectively flat… and utilities were treated as bond substitutes
rather than growth vehicles. That era is over.”
I do not yet know whether I am right about this one. I wrote it in January.
Eight months is not a track record, and anyone who tells you otherwise is selling you
something.
What I can do is show you what has happened since — in the filings, in the capacity
market, and in the earnings of the companies on this map. That is the rest of this letter.
It Is Already Showing Up in the Earnings
This is the part where a letter like this usually asks you to take the story on faith.
I would rather show you the filings.
When every company in the portfolio had reported its most recent quarter, I went through all of
them line by line, as I do every quarter. Here is what came back:
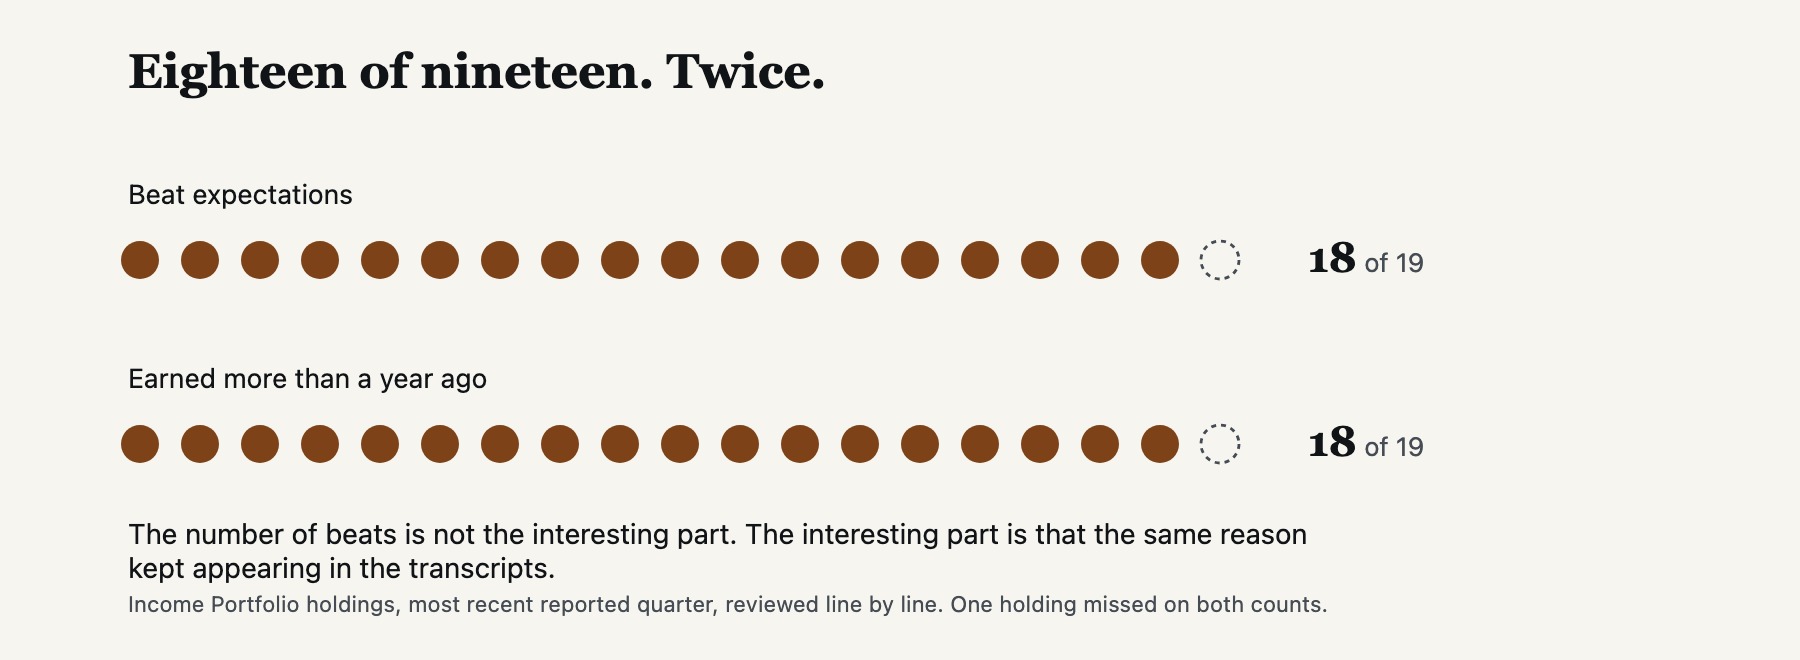
Eighteen of the nineteen holdings in the Income Portfolio beat expectations. Eighteen of
nineteen earned more than they did a year ago.
It was one of the strongest earnings seasons this portfolio has had in some time. But the
number of beats is not the interesting part. The interesting part is that the same
reason kept appearing.
69 gigawatts of new demand through 2030
The largest transmission network in the United States has already locked up roughly 13
gigawatts of generating equipment to serve it — and raised its full-year guidance
while doing so.
Roughly 60% demand growth by 2031
An upper-midwest utility, with three large data center projects already in construction
— not proposed, in construction.
$7.6 billion earmarked for data center infrastructure
A Midwest gas and electric utility, inside a $28.6 billion five-year capital program. It
has regulatory approval for agreements with Amazon and Alphabet, and management says
those agreements should generate $1.4 billion in savings for existing customers. Its
long-term earnings growth target is 9–10% a year through 2033 — which, for a
regulated utility, is a remarkable thing to put in writing.
“Beginning to show up in the numbers”
A central-plains utility reported that large new customers, data centers among them, are
“beginning to show up in the numbers rather than merely in the development
pipeline.”
That last phrase is the entire story in one line, written by a utility’s own management.
The demand stopped being a projection and started being revenue.
And a midstream partnership in the portfolio told investors to expect distribution increases of
12.5% in each of the next two years — which is the same event, arriving in your account
as cash.
The record
12% a Year Since 2019 — and the Worst Year Was Down 5.6%
2025
Return
Yield
Income Portfolio
10.7%
4.8%
Growth Portfolio
16.5%
—
S&P 500
16.5%
—
Utility index
14.9%
—
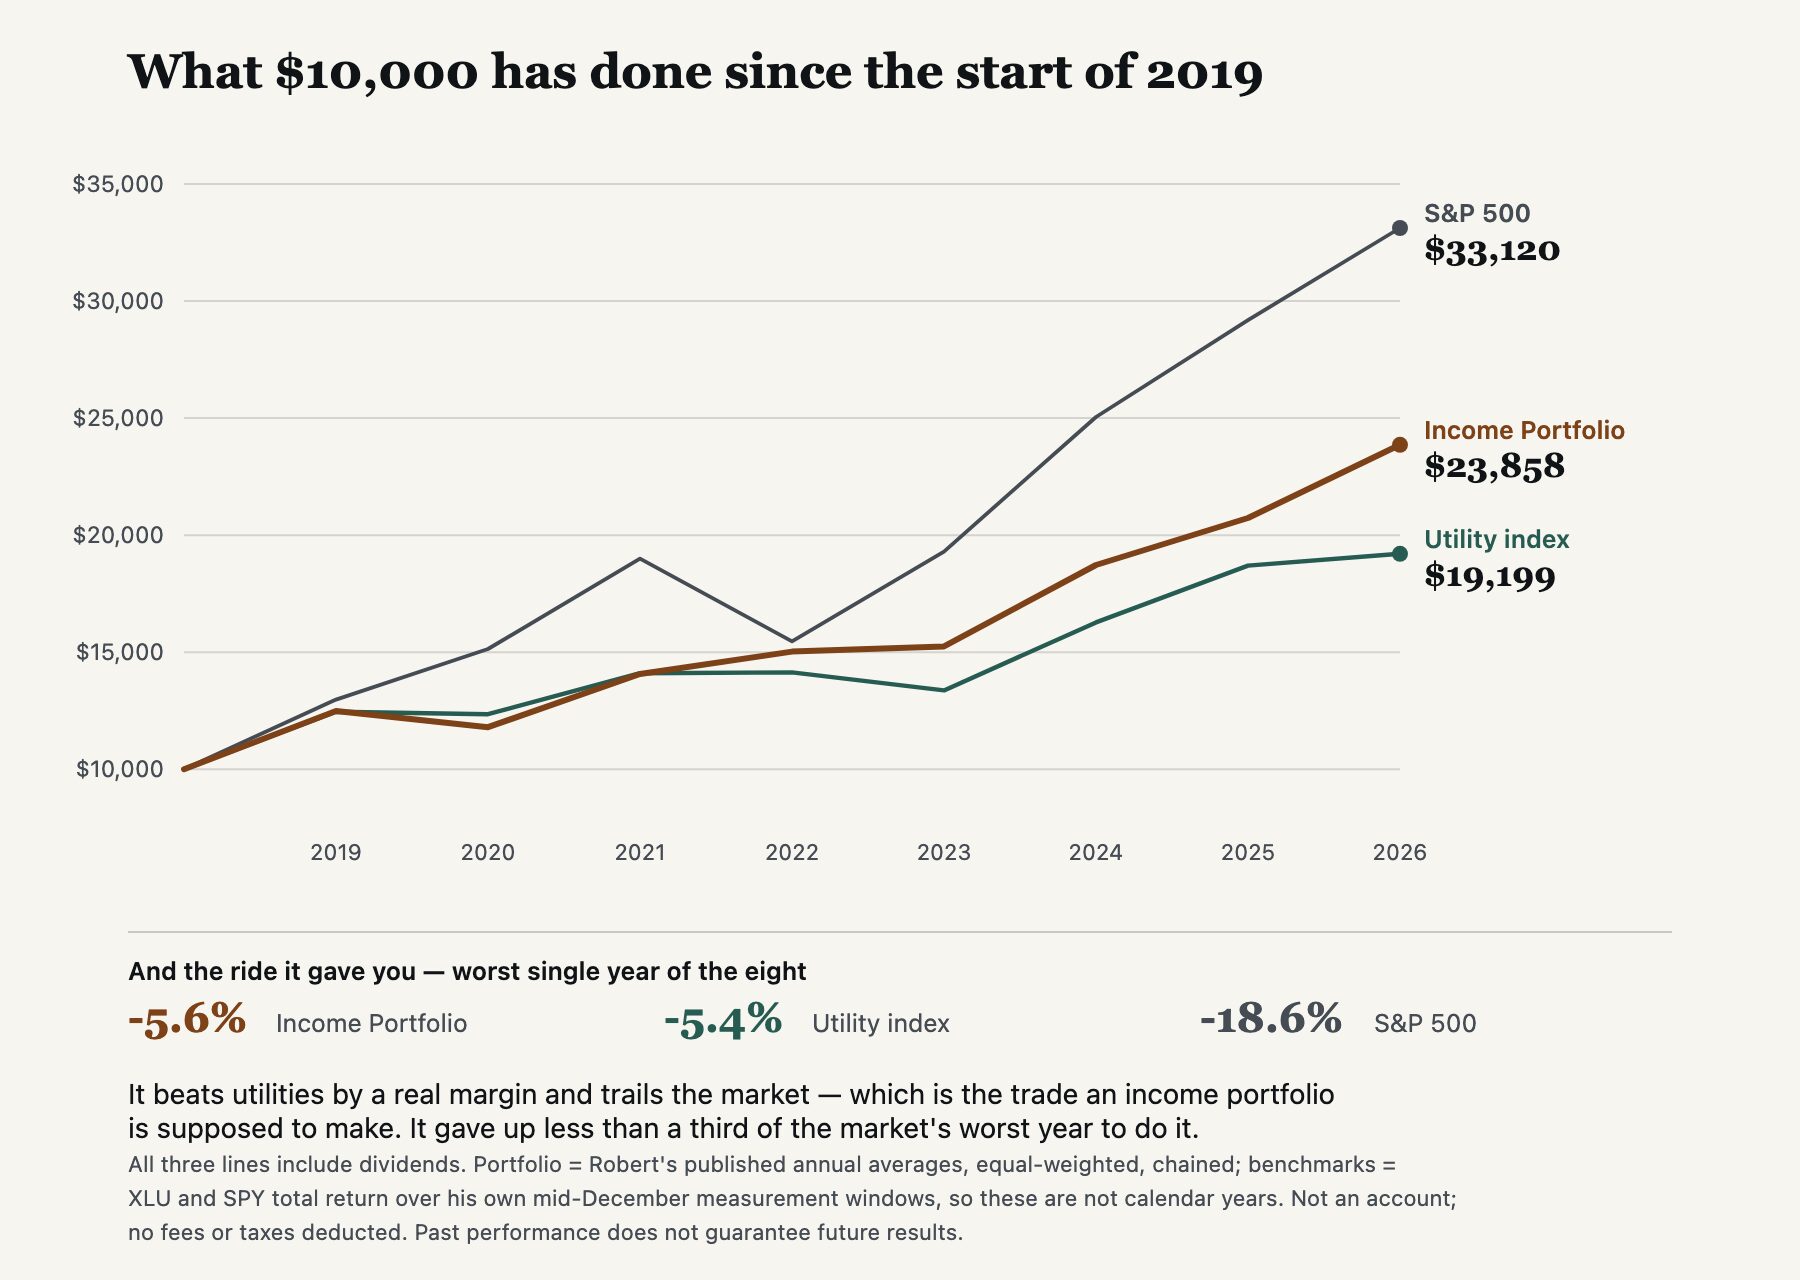
Since the start of 2019 — seven and a half years — the Income
Portfolio has compounded at roughly 12% a year. The utility index over the
same stretch, with its dividends counted the same way mine are:
8.9% a year.
Nearly a quarter more than the utility index over seven and a half years — and it gave
up less than a third of the market’s worst year to get there.
Benchmarks are total return — dividends included — measured over the same
mid-December windows I close my own books on. A price-only utility index would flatter these
numbers by about three points a year, and I would rather you saw the harder comparison.
It trails the S&P 500 over that period, and it is supposed to. A portfolio built to fall
less in the bad years will not lead in the good ones. That is the trade, and I would rather
state it plainly than let you find it out on your own.
So far in 2026, the Income Portfolio is up 15.1% —
ahead of both the S&P 500 and the utility index, which is unusual for a portfolio built
this way and worth noting precisely because it is unusual. The Growth Portfolio is up 5.1%,
behind both. I would rather tell you that than average the two into a single number that
describes neither.
And 2020 was a losing year. The Income Portfolio fell 5.6%. I wrote that in
the year-end review at the time, and I am writing it here.
Portfolio figures are the simple average return of the holdings in each portfolio over the
review period, equal-weighted — not position-sized or dollar-weighted. Review periods run
mid-December to mid-December, not calendar years. Holdings changed from year to year, and both
portfolios were re-sorted in December 2020, so multi-year figures chain baskets that were not
identical. No individual subscriber’s account returned these numbers. Past performance
does not predict future results. Figures as of August 28, 2026.
90-day money-back guarantee. Cancel any time. The reports are yours either way.
Every dividend on this map is a promise a company makes with money it has to genuinely earn.
Sometimes a company stops being able to keep that promise. The dividend gets cut, and the share
price usually goes with it — which is how income investors get hurt twice in one
afternoon.
So after every earnings season I run every holding through what we call the
Early Warning System.
It takes a company’s return on equity apart into its component pieces, so I can see what
is actually driving it: whether a business is improving because it has genuinely become more
profitable, because it is using its assets better, or simply because it has taken on more debt.
That last one looks identical to the first in a headline number, and it is the one that kills
dividends. Then I look at the trend across several quarters, because one bad quarter in a
seasonal business means nothing.
Here is it working, this month.
Flagged
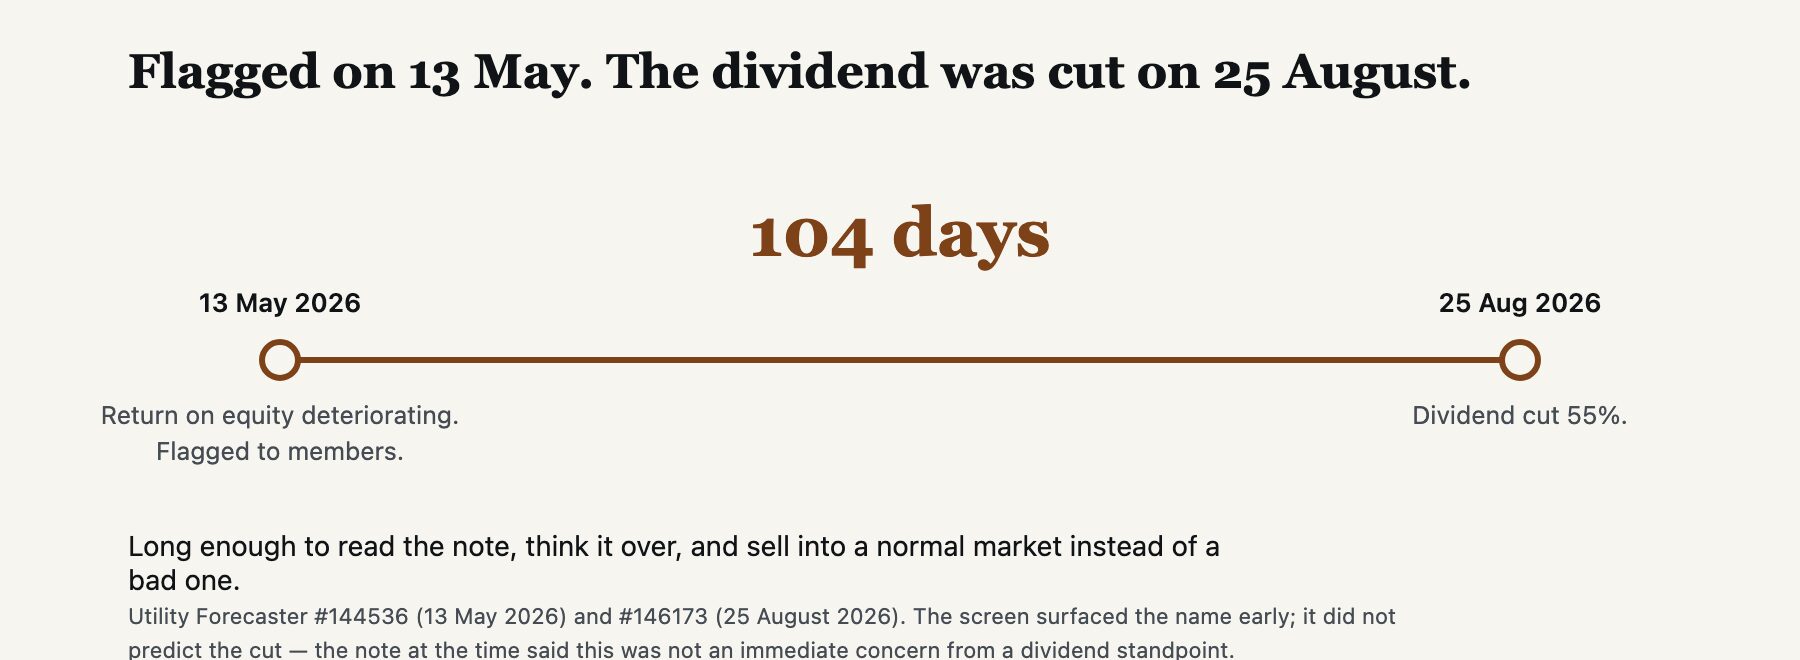
One holding — a Canadian telecom operator — came back badly deteriorated. Its
return on equity had gone from slightly positive to negative 11.3%. The
company had taken a large write-down, reduced its outlook, and shortly afterwards
reset its dividend 55% lower.
A second, a propane and gas distributor, went from 9.6% to negative 2.6%. It
is on the watch list and I said so.
And two more came back looking alarming and were not. Both readings were
distorted by one-off accounting charges rather than any deterioration in the underlying
business. I said that too, and explained why — rather than frightening anyone out of a
perfectly healthy company on a bad-looking number.
That is the job. Not pretending nothing ever goes wrong here. Things go wrong.
The job is telling you which is which, in writing, before it costs you money.
Robert Rapier avoids the sensationalism of many investing publications. He will admit to
mistakes, is willing to change as the landscape moves against positions or industries, and
looks to make reasonable returns with a generally conservative approach.
Stephen Bechwar · subscriber survey, 2021
What You Won’t Get From Me
Let me tell you what you are not getting. I would rather lose you here than have you join and
find out later.
This is not a trading service
There are no daily positions, no options, no leverage, nothing with an expiry date. In a
typical year the portfolio changes very little. If you want something to do every day, this is
the wrong service — and I would rather you knew that now. Every trade costs you in
commissions, spreads and taxes. Doing less of them is a feature I charge for.
It will not beat the stock market in a bull market
And it is not designed to. Over the last seven and a half years the Income Portfolio has
compounded at roughly 12% a year. The S&P 500 did better. It also had a year down
18.6% in that stretch. My worst was down 5.6%. That trade
— most of the return, a far shallower hole to climb out of — is the entire point,
and if you want maximum return you should buy an index fund and stop reading.
It is not protection against a crash
I want to be very clear about this, because our industry lies about it constantly. In 2020,
utilities fell further than the S&P 500 and took far longer to recover.
Anyone who tells you utility stocks are a hiding place has not looked at the data.
We have losing years
2020 was one; the Income Portfolio fell 5.6%. We have had losing positions too. The worst was a
wood-pellet producer that fell roughly 95% before we were out of it. I wrote at the time that I
do not intentionally make speculative picks in this letter — because that one was —
and that I had kept it to a small percentage of the portfolio for exactly that reason. Both
those things were true, and neither of them made it hurt less.
And nothing here is a guarantee
Dividends are declared by boards of directors, quarter by quarter, and boards can cut them.
What I can promise is the screen you just read about — run on every holding, every
quarter, whether or not anything looks wrong.
We Started When the Berlin Wall Was Still Standing
That means something in a business where advisory letters appear and vanish constantly. Over
the years I have watched newsletters launch for dot-coms, day trading, penny stocks,
cryptocurrency, solar, biotech, nanotech and emerging markets. Most of them are gone, along
with the fashion that produced them.
We have never been fashionable. We are not fashionable now.
But essential-service companies do not go out of style, because nobody stops needing
electricity — and a business model that survived the dot-com collapse, the financial
crisis and two decades of flat demand is not likely to be undone by the next thing.
Some of our readers have been with us for decades.
I really trust Robert Rapier. I believe he puts the investor’s best interest first,
he does extensive research, and he wants the investor to be successful.
Anna Kunze · subscriber survey, 2021
If you want income and capital growth at reasonable risk, and low anxiety, Utility
Forecaster is a good source of ideas.
Charles Payton · subscriber survey, 2021
Buy income-producing stocks. If a company can pay the dividend, they must be making money.
Joe Lindell · subscriber survey, 2021
“What If I’m Already Retired?”
This is the question I get most often, and it is usually asked apologetically, as though it
were an admission. It is the most sensible question on this page.
Everything I have shown you so far involves decades. A water utility bought in 1994. A
compounding curve that takes thirty years to reach a number that sounds impossible. If you are
sixty-eight, it would be reasonable to read all of that and conclude the arithmetic is for
somebody else.
So let me be direct: you are not buying a thirty-year plan. You are buying a payment.
A new position in the Income Portfolio starts at roughly a 4.5% yield. Not in
2056 — next quarter. That payment arrives whether the market is up, down, or closed for
the holidays, because it is funded by people paying their electricity bills.
Then it grows on its own. Eight of the companies on this map raise their dividend
every autumn, five of them without missing a year since 2019. You do not have to do
anything to receive those raises. You do not have to time them, or trade around them, or read
a single one of my issues. You have to own the stock.
And here is the part that matters more at sixty-eight than it ever did at forty-five.
In the worst year of the last eight, this portfolio fell 5.6%. The
S&P 500’s worst year over the same stretch was down 18.6%. When you
are still working and adding money, a
violent year is survivable and occasionally useful. When you are withdrawing, it is
the single thing most likely to ruin you: selling into a decline to cover your expenses
permanently destroys capital that a recovery can never bring back.
A portfolio built to swing less is not a consolation prize for people who missed the exciting
returns. For someone drawing an income, it is the entire point.
You are late to the 48.6%. I will not pretend otherwise — that number belongs to a
position bought in 1994 and held for thirty-two years, and anyone who suggests you can have it
by 2028 is selling you something.
But the 1994 buyer had twenty years of flat demand ahead of them, and still got here. You have
the largest expansion in American electricity demand since 2000, arriving at businesses that
are permitted to earn a return on every dollar they invest to meet it.
And if it turns out that the compounding runs longer than you do — these are shares.
They pass to whoever you leave them to, still paying, still raising. That is not a morbid
thought. It is the most ordinary form of wealth there is.
Miss the Cutoff and You Wait a Full Quarter
Your first payment can arrive in a matter of days.
That is the whole difference. For anyone buying these companies for the reason we buy them
— the income, and what the income does when it compounds for thirty years — that
difference is not small. It is where the compounding starts.
A dividend has a cutoff. Every company on this map sets a date you have to own the stock before it to receive that payment. Own
it the day after and you are not paid late. You are simply not paid at all, until the next
quarter.
Eight of the companies on this map have already declared their next cutoff.
The next one lands in days, not months — the Bismarck, North Dakota
multi-utility we bought in 1990, which has been paying us 39.5% a year on what we originally
invested.
September 10
Bismarck, North Dakota
September 11
Wyomissing, Pennsylvania
September 14
Dover, Delaware
September 15
King of Prussia, Pennsylvania · Minneapolis, Minnesota
September 29
Oakville, Ontario · Calgary, Alberta
October 7
Philadelphia, Pennsylvania
Eight cutoffs inside the next four weeks, and the first of them is days away.
The map is in the report. The payment dates are on the companies’ own investor pages. You can
check every one of them before you decide.
Ex-dividend dates as declared by each company, as of September 9, 2026. Only declared dates are listed. Dates are set by the
companies and can change; check the issuer before acting.
Your membership
What You Get Today
Report one $99 value
The Incredible Dividend Map: Where Stocks Yield Up to 48.6% on Every Dollar Invested
All 33 cities, every company on the map, what each one has returned, and what each now pays on the money originally invested — with a short profile of each business.
Report two $99 value
Robert’s 2026 Essential Income Portfolio
Your income portfolio, pre-built. The ten companies I would buy first if I were starting from nothing today, with what to pay for each.
Report three $99 value
The Infrastructure Opportunity
Where the 2026 income is headed, and why.
Report four $99 value
5 Utilities for AI Power Demand
The supply side of the AI story — the companies almost nobody is buying.
Report five $99 value
The Dividend Compounding Blueprint
How to turn today’s yield into double-digit income on cost, step by step. This is the yield-on-cost section of this letter, worked out in full.
Five reports · $495 of research, included free with a $49 membership.
Full portfolio access — all 42 dividend payers
Every name, every buy-under price, every current yield, plus the five-position
fixed-income sleeve.
52 weekly issues, plus urgent portfolio updates
Me in your inbox every Friday. Immediate notices whenever a position needs action.
The Early Warning System, run every quarter
Every dividend in the portfolio through a full financial screen after each earnings
season — the same screen described above.
The “How They Rate” table — nearly 390 companies
Our assessment of every essential-service company we track, not just the ones we own.
Your price
$49 for Your First Year
Regular Rate · 1 Year
$99
12 months · our standard membership rate
Full portfolio access (all 42 dividend payers)
52 weekly issues, plus urgent portfolio updates
The Early Warning System, run every quarter
The “How They Rate” table (nearly 390 companies)
90-day money-back guarantee
Bonus reports ($495 value) not included
★ Best value · Save 50%
New-Member Rate · 1 Year
$49
12 months · less than a dollar a week · 50% off the $99 rate
Full portfolio access (all 42 dividend payers)
52 weekly issues, plus urgent portfolio updates
The Early Warning System, run every quarter
The “How They Rate” table (nearly 390 companies)
90-day money-back guarantee
Plus, included free: all five bonus reports — a $495 value
That is less than a dollar a week for the research behind a portfolio whose Income side has
compounded at about 12% a year since 2019.
Start your membership
$49 for your first year · all five reports included · 90-day money-back guarantee
Please read this before you order. Your membership is one full year of
Utility Forecaster for $49. After that first year it renews automatically at $99 a
year, charged to the card you use today. We will email you before that happens, and you can
cancel any time — in one click, or by replying to any issue. If you cancel inside the
first 90 days you get every dollar back and you keep all five reports.
My Double Guarantee
90 days, no questions
Join today. Download everything. Read every issue. If at any point in the next 90 days
you decide this is not for you — any reason at all, or none — email
customerservice@investingdaily.com
and we will refund your subscription in full. Not a pro-rated portion. The entire fee.
You keep the reports
Even if you refund. The Map, the Essential Income Portfolio, all five of them. Yours, as
thanks for giving us a try.
You cannot lose money finding out whether this is for you. That is the point of structuring it
this way.
Questions
Before You Decide
What do I get, and when?
Everything, within about five minutes of ordering. All five reports, the full portfolio
with every name and buy-under price, access to the members’ site, and your first
weekly issue this Friday.
How much could I make?
Nobody can tell you that honestly and I am not going to try. What I can tell you is what
has happened: since 2019 the Income Portfolio has compounded at about 12% a year against
the utility index’s 8.9%, with one losing year in that stretch. A new position
today starts near a 4.5% yield and grows from there. All investing carries the risk of
loss.
Do I need a lot of money to start?
No. These are ordinary stocks in ordinary brokerage accounts, and several of the largest
positions on this map trade well under $100 a share. The strategy works the same at
$5,000 as at $500,000 — what it needs is time, not size.
How much work is this?
Very little, and that is deliberate. You will not trade often. Every trade costs you in
commissions, spreads and taxes, and the point is for us to get richer rather than our
brokers.
Why is it only $49 when it is normally $99?
Because members who see how the research works tend to stay for years, some of them since
the late 1980s. A discounted first year is how we earn that rather than argue for it.
Yes. Investing Daily’s customer care is staffed by real people in the United
States.
customerservice@investingdaily.com,
or (800) 832-2330, 9:00 a.m. to 5:00 p.m. Eastern, Monday through
Friday.
Is my order secure?
Yes — the order form uses bank-level encryption and we never sell your email
address.
Your first year is $49, and you have 90 days to decide whether it was worth it.
I want to close by being precise about what waiting costs, because it is not what most letters
tell you it is.
It is not that the prices run away from you. They might, or they might not, and anyone who
tells you they know which is guessing.
It is that the compounding does not start until you own the shares.
A quarter you spend deciding is a payment you do not receive, and it is also a payment that
never joins the pile that grows the year after. That is the whole engine. It only runs forward,
and it only runs for people who are in it.
Eight of the companies on this map have already declared their next payment date.
The first is days away. That is not a sales deadline — it is a date the companies set,
published on their own investor pages, and you can check every one of them before you decide.
What I am offering you for $49 is not a stock tip. It is the three things I have spent this
letter showing you, in one place:
Income that starts next quarter and grows most years without you lifting a
finger. Growth from the largest expansion in American electricity demand since
2000, owned through the companies that expansion cannot happen without — rather than
through a guess about which technology company wins. And safety: a portfolio
whose worst year of the last eight was down 5.6%, against the market’s 18.6% —
screened every quarter for the one thing that
actually hurts an income investor, by someone who will tell you when he gets it wrong.
Less than a dollar a week. Ninety days to decide whether I have earned it. The reports are
yours either way.
Sincerely,
Robert Rapier
Chief Investment Strategist, Utility Forecaster
P.S. The mechanism on this page is not complicated and it is not new. It is what happens
when a company that has to keep the lights on raises its dividend a little every year, and
somebody holds on long enough for that to matter. What is new is the demand. For twenty years
these businesses had almost nowhere to grow, and they got us here anyway. That just changed
— and it is already in their filings, not just in their forecasts. The map is $49, eight
of these companies have already set their next payment date, and you have 90 days to send it
all back.